Gemfields expects interim net loss to widen to $73m, but recoveries improving
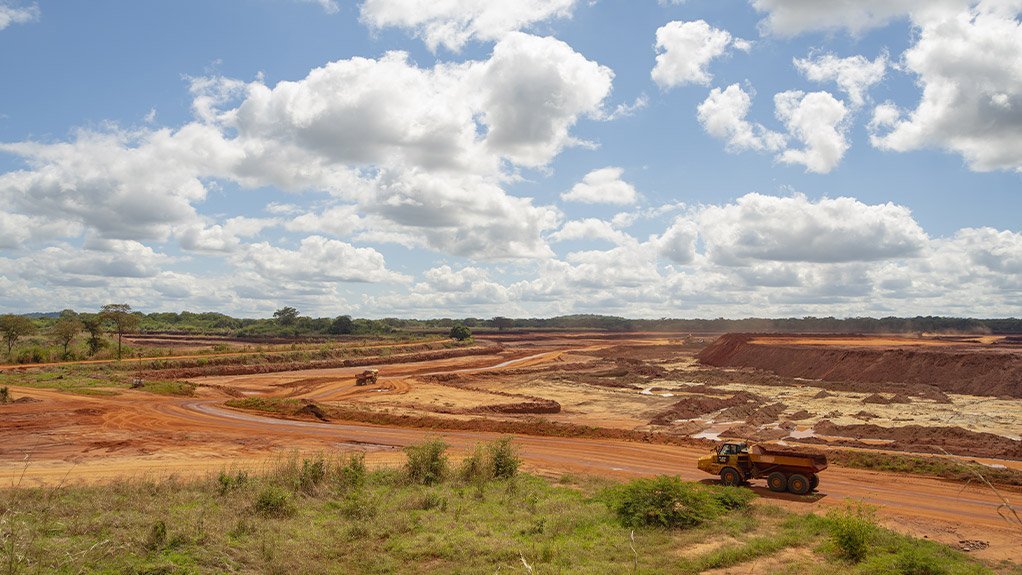
Gemfields has reported that its key operating assets, Montepuez Ruby Mining (MRM), in Mozambique, and Kagem Mining, in Zambia, generated revenues of $76.1-million and $26.7-million respectively in the six months to June 30, compared with $38.9-million and $21.1-million respectively for the same period last year.
Total auction revenues for the six months ended June 30 were $102.8-million.
The company reports that auction revenues were significantly higher than the prior period, reflecting the deferral of a mixed-quality ruby auction from December 2025 to February 2026, which reduces the comparability of the respective periods.
Gemfields says it is reasonably certain that its net loss after tax will be $73.5-million for the six months ended June 30, compared with a net loss after tax of $20.5-million in the same period last year.
In rand terms, the net loss after tax is expected to be R1.21-billion, compared to a net loss after tax of R363.2-million for the first half of 2025.
The expected net loss after tax was driven primarily by a non-cash impairment charge of $125.2-million recognised in respect of MRM.
In addition, the company notes that the financial year 2025 impairment has been restated from $35-million to $65-million following the identification of a $30-million adjustment.
Further details of the restatement will be provided in the interim financial statements, which are due for release on September 30.
Gemfields says the impairment reflects the more conservative approach to forecasting grade recoveries taken in the period, particularly for premium product, following lower-than-expected recoveries during the period.
While uncertainty remains, the company says recent operational performance indicates that premium-grade recoveries are beginning to improve following actions taken by management.
Gemfields says the group will continue to monitor grade recoveries closely as additional production data becomes available.
“The first half of 2026 was a challenging period for Gemfields, driven by lower-than-expected premium ruby recoveries at MRM, which had a significant impact on the group’s financial performance.
“Management’s primary focus has been to understand the causes of these lower recoveries and implement measures to improve grade performance, mine planning and operational reliability,” says interim CEO David Lovett.
While further evidence is required before drawing firm conclusions, Lovett says the company is encouraged by the early signs emerging from these initiatives.
He explains that PP2 has now demonstrated its ability to achieve, and on occasion exceed, design throughput levels, although final commissioning and optimisation activities are still underway.
Additionally, recent ruby recoveries have shown early signs of improvement.
Kagem, meanwhile, delivered solid operational performance and good premium emerald recoveries during the period, albeit against a backdrop of elevated operating costs, says Lovett.
“Our priority for the remainder of 2026 is to demonstrate that the recent improvements at MRM can be sustained, while maintaining financial discipline and flexibility across the group.”
Gemfields expects its loss a share to be $0.043, or R0.71, for the period under review, compared with a loss a share of $0.017, or R0.30, in the prior corresponding period.
Headline earnings, however, are expected to recover to $0.006 apiece, compared with a headline loss of $0.015 in the prior comparable period. In rand terms, the prior interim headline loss of R0.26 will likely improve to headline earnings of R0.098 apiece.