A 36-Year Shock to the Aluminum Market; Empty LME Warehouses Fall Under the Monopoly of Russian Metal
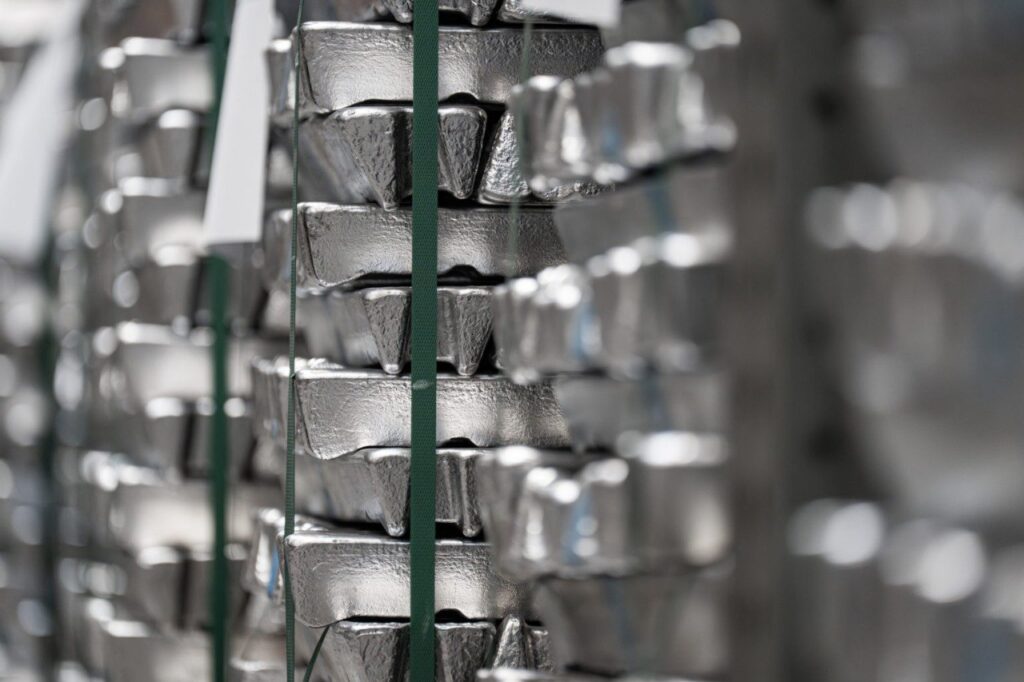
The global aluminum market is facing the most severe short-term supply crunch in the past 36 years; the $176.80 per ton premium of the cash price over the three-month contract on the London Metal Exchange (LME) has pushed the spread between cash and futures prices to its highest level since November 1990.
This situation reflects the more than 50% depletion of official warehouses since the beginning of this year and has placed this strategic metal on the verge of an acute settlement squeeze; an event that, with deliverable stocks concentrated in Russian cargoes and an unprecedented dominance of a single player over warehouse warrants, has sounded the alarm for industrial buyers and holders of short positions.
Inventory Retreat and Unprecedented Surge in the Cash Spread
Based on Thursday’s trading, the structure of the aluminum market on the London Metal Exchange entered a condition unprecedented in the past 36 years. While the benchmark three-month contract price (CMAL3) fell 1.4% to $3,027 per ton, buyers of immediate delivery were willing to pay $176.80 above the three-month maturity to obtain cash ingots; this steep backwardation is a direct reflection of traders’ urgency to secure physical goods in the short term.
Monopoly of Russian Metal in Half-Emptied Warehouses
The driving engine of this crisis is the continuous depletion of LME warehouse inventories; stocks that have fallen by more than 50% since January, reaching the fragile figure of 226,350 tons. However, the crisis is not limited to tonnage reduction; data indicate that available and valid (on-warrant) inventory is almost entirely allocated to aluminum of Russian origin.
London Metal Exchange
Oday Patel, a senior analyst at Wood Mackenzie, in explaining this complex structure, says: “The reality is that the aluminum price discovered on the London Metal Exchange is now effectively the price of Russian metal, since no other origin remains in these warehouses.”
Hoarding of Warrants and Settlement Squeeze at the November Maturity
What has made the market fire burn hotter is the dominance of a single player over 30 to 39 percent of all aluminum warehouse receipts and warrants on the London Metal Exchange. This ownership concentration has cornered traders holding short positions in the November contract; players who have only until the final settlement next week to either find physical metal for delivery or roll over their positions to future maturities at heavy cost.
At the same time, the waves of this shortage have crossed Europe’s borders and pushed the Shanghai Futures Exchange (ShFE) into backwardation as well; such that the Shanghai November contract is trading at a 350 yuan ($52.50) premium over December, indicating that the race to acquire deliverable metal is a pervasive trend on a global scale.